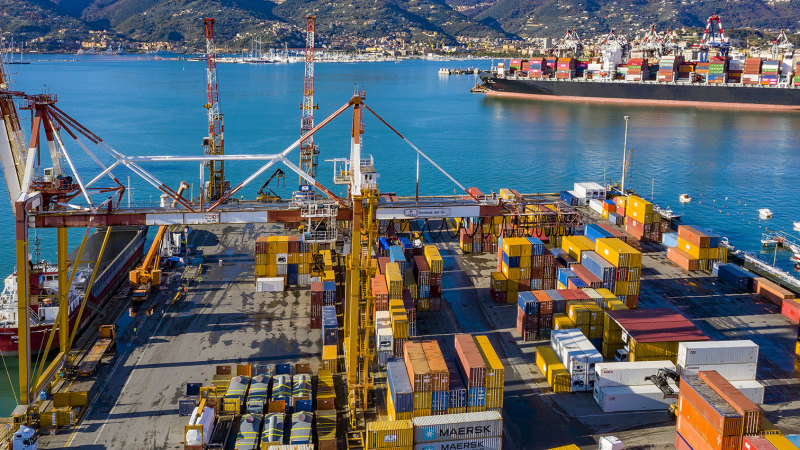

The closure of Chinese factories during the Golden Week holidays has dampened demand for container shipping on the main east–west trade routes, prompting shipping lines to cancel several sailings on transpacific and Asia–Europe services. The impact on spot freight rates is reflected in Drewry's World Container Index: in its update published on Thursday 8 October 2026, the composite index – an average across all routes – fell to $4,351 per 40-foot container, down 2% week on week. This marked the second consecutive decline, following $4,468 on 24 September and $4,434 on 1 October, although the index remained 164% above its level a year earlier.
The sharpest decline was recorded on the Shanghai–Los Angeles route, where rates fell 3% to $7,624 per FEU, while Shanghai–New York dropped 2% to $10,220. These two routes also recorded the largest year-on-year increases in the index, at 250% for Los Angeles and 220% for New York. Drewry's Container Capacity Insight service reports four cancelled transpacific sailings for next week, compared with eleven this week, indicating an increase in available capacity. On the demand side, an extension of the US–China trade truce could support a recovery in US-bound volumes after the holidays, according to the consultancy, which expects rates to remain stable over the next seven days.
On the Asia–Europe trade, Shanghai–Rotterdam rates declined 2% to $3,337 per FEU, while Shanghai–Genoa remained virtually unchanged at $3,696, compared with $3,702 the previous week. Both routes have more than doubled their rates over the past twelve months, with increases of 112% for Rotterdam and 106% for Genoa. Announced sailing cancellations for next week have risen from five to six, slightly reducing scheduled capacity. The trend is reversed on the return legs to Asia: Rotterdam–Shanghai rates rose 2% to $628 per FEU, while Los Angeles–Shanghai increased by the same percentage to $806. On the transatlantic trade, rates fell 1% in both directions, reaching $1,106 from New York to Rotterdam and $3,091 in the opposite direction.
According to Drewry, the main threat to carriers' efforts to support rates on the Asia–Europe trade, which have been falling for thirteen consecutive weeks, is the return to the Suez route. This has happened faster than expected, with increased transits through the canal adding capacity to the trade lane, although uncertainty surrounding Houthi attacks remains. Drewry also expects rates on this route to remain stable next week. Shipping lines are seeking to reverse the downward trend by introducing higher FAK (freight all kinds) rates in the second half of October, but the consultancy considers their effective implementation uncertain.
M.G.