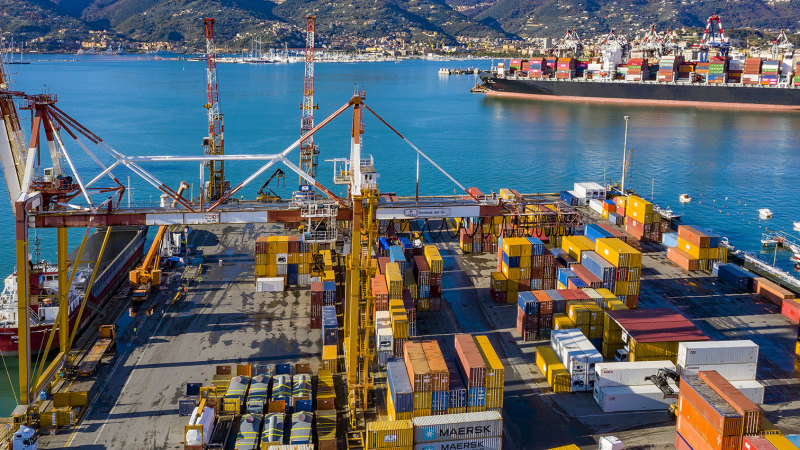

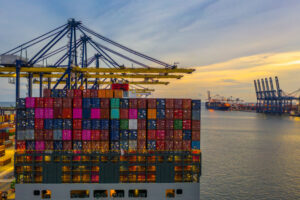
After two weeks of increases, average spot container shipping rates, tracked by Drewry’s World Container Index (WCI), have reversed course. In its weekly assessment published on 29 October 2026, the composite index stood at $4,429 per 40-foot container, down 3% from $4,585 the previous week. The decline was driven mainly by transpacific routes, with Shanghai–Los Angeles falling 6% to $7,514 per FEU and Shanghai–New York dropping 5% to $9,631. Against this backdrop, shipping lines have announced six blank sailings for the following week, up from five in the current week. Drewry’s Container Capacity Insight interprets this as a sign that capacity remains constrained. However, US import demand is cooling: the National Retail Federation forecasts an 11% month-on-month decline in US seaborne import volumes in November, potentially putting further downward pressure on freight rates. Drewry expects another decline in its next assessment.
On Asia–Europe routes, Shanghai–Rotterdam rates rose 1% to $3,686 per FEU, while Shanghai–Genoa remained unchanged at $4,151. Announced blank sailings for the following week have fallen from eight to four, increasing effective capacity. Carriers have announced increases in Freight All Kinds (FAK) rates for November, but Drewry doubts these increases will hold, given available capacity and weak demand, and expects rates to remain stable. The decline also extended to the Atlantic, where rates fell 2% in both directions. Rotterdam–New York dropped to $3,106 per FEU, although this was still 85% higher than a year earlier, while New York–Rotterdam fell to $1,135, up 34% year on year. On return routes to China, Los Angeles–Shanghai declined 1% to $837, while Rotterdam–Shanghai remained unchanged at $646, 40% above its October 2025 level.
Drewry expects weak demand and carriers’ capacity decisions to continue influencing freight rates. It identifies subdued demand, carrier capacity management, potential surcharges and developments in US trade policy as key factors in the coming weeks. As for disruption hotspots in container shipping, the Suez Canal recorded 62 transits in the previous week, its highest weekly figure of 2026, while difficulties persist in the Strait of Hormuz, where only two vessel transits were recorded. In China, congestion at the port of Shanghai is easing, although the passage of Typhoon Champi could interrupt this improvement.
M.G.