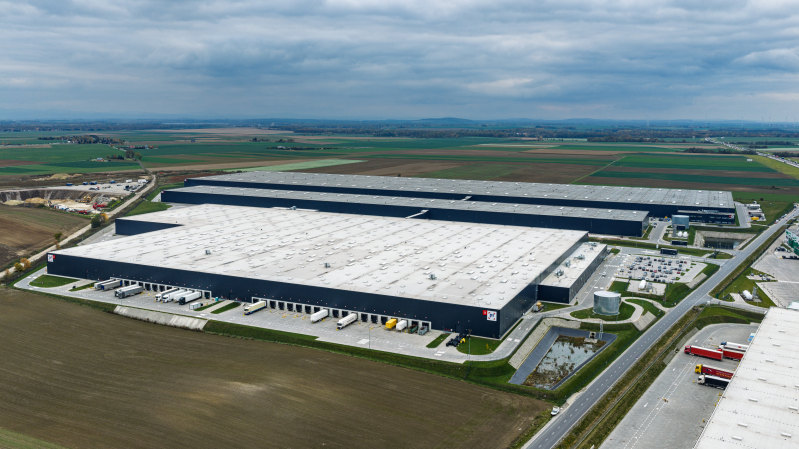



The reliability of electricity supply is the most important factor in choosing the location of a future logistics facility, cited by 38% of executives surveyed by The Harris Poll on behalf of Prologis, compared with 31% for transport access and 29% for automation readiness (respondents could select up to three factors). The findings are contained in the Prologis Global Supply Chain Outlook 2027, published on 5 November 2026, the third edition of the annual study. The online survey, conducted between 3 and 20 August 2026, involved 1,821 supply chain executives at director level or above, working for companies with more than 250 employees. The non-probability sample covered the United States (519 respondents), the United Kingdom, Germany, India, China and Mexico.
Two-thirds of executives report that energy has a significant impact on supply chain operating costs, with electricity bills (39%) and transport fuel (39%) the most frequently cited expenses. Half of companies now routinely factor energy surcharges into site and lease assessments, while 95% consider the reliability of energy infrastructure when selecting a property. To ensure continuity of supply, companies have launched or accelerated investments in battery energy storage systems (43%), flexible demand and load management (41%), on-site backup generation (40%) and long-term renewable energy agreements (40%). To protect margins, 59% are funding efficiency improvements and 49% are securing multi-year energy contracts.
Only 23% of companies have achieved energy independence through on-site generation (four percentage points fewer than the previous year), while 58% have comprehensive backup systems (+12 points), 13% have backup limited to essential services (-8 points) and 5% have minimal or no backup systems. Most companies affected by energy crises report that their measures have proved effective, but more than a third remained exposed to events such as regional power grid failures or prolonged price volatility. Prologis identifies natural gas supply disruptions, cited by 41% of respondents, and maritime shipping crises, cited by 40%, among the events highlighting supply chain vulnerabilities. According to Prologis, the supply of logistics properties equipped with adequate energy infrastructure is failing to keep pace with demand.
Same-day delivery is now offered by 58% of companies, compared with 24% in 2019, and 91% of respondents say it has become a basic consumer expectation in their sector. For 39% of respondents, delivery speed and reliability are the leading means of differentiating their company from competitors, more than twice the proportion citing competitive pricing (18%), while product range accounts for 15%. Some 84% recognise a gap between what retailers promise and what warehouses can actually deliver, while 91% acknowledge that consumer expectations for speed are rising faster than supply chains can adapt. To meet promised delivery times, 92% are investing in last-mile innovation, 91% believe more decentralised order fulfilment networks are needed and 88% expect early adopters of drones to gain a significant advantage in certain markets. Prologis sees these expectations translating into growing demand for logistics facilities closer to consumers.
Some 67% of executives believe that artificial intelligence already differentiates their company from competitors: 34% report a moderate advantage and 33% a clear competitive lead that is driving market share growth. Almost one company in ten (9%) is using AI to take market share from larger operators, 15% say they are keeping pace with the industry and another 9% are losing ground because competitors have adopted the technology. The most widespread applications concern operational efficiency (58%), workforce augmentation (49%) and customer experience (49%).
Which technologies are likely to have the greatest impact on supply chains? Looking three years ahead, respondents expect AI-powered demand forecasting (43%) and agentic AI systems (39%), capable of carrying out tasks and managing decisions with considerable autonomy, to be the most transformative. Some 75% of companies plan to invest significantly in demand forecasting and inventory replenishment solutions over the next two years, while 71% expect to invest in agentic AI systems. However, several factors could hinder the large-scale adoption of artificial intelligence: integration with legacy systems (27%), cybersecurity (26%) and upfront costs (23%). Over a five-year horizon, respondents expect these investments to deliver greater speed and throughput in logistics and order fulfilment (49%), improved disruption prediction and response capabilities (47%) and end-to-end supply chain visibility (45%).
The main factors that could disrupt operational continuity are customs tariffs (55%) and conflicts along major maritime shipping routes (53%). For two-thirds of executives, tariffs have changed the pace or scope of regionalisation plans, prompting companies to accelerate implementation, begin planning or revive suspended initiatives. In the August 2025 survey, 77% had already established regional networks, while the proportion maintaining their existing global configuration has fallen by 15 percentage points to 36%. During 2025, more than half of companies changed their transport routes and distribution network structures: 54% reorganised supply chains on a regional basis, 36% opted for nearshoring and 35% pursued reshoring. In response to geopolitical disruption, 76% of respondents rate their supply chains as highly agile, 34% describe their planning approach as "aggressive transformation" (ten percentage points more than the previous year) and 93% agree that by 2030 agility will be a more important source of competitive advantage than cost efficiency. Regionalisation also has regulatory implications: two-thirds of executives report a significant impact from local regulations, with emissions standards exerting the greatest pressure.
Antonio Illariuzzi